If you keep ₦200,000 or ₦500,000 in a regular Nigerian commercial bank savings account for emergencies or an upcoming project, you already know the frustration. Every month, SMS alert charges, card maintenance fees, and inflation chip away at your balance. Worse, if you transfer money out of that savings account more than four times in a single month, Central Bank of Nigeria (CBN) rules allow your bank to pay you zero interest for the entire month.
You might want the higher yields that banks and wealthy investors earn on Nigerian Treasury Bills, but bidding directly at a CBN primary auction requires a minimum of ₦50,001,000.
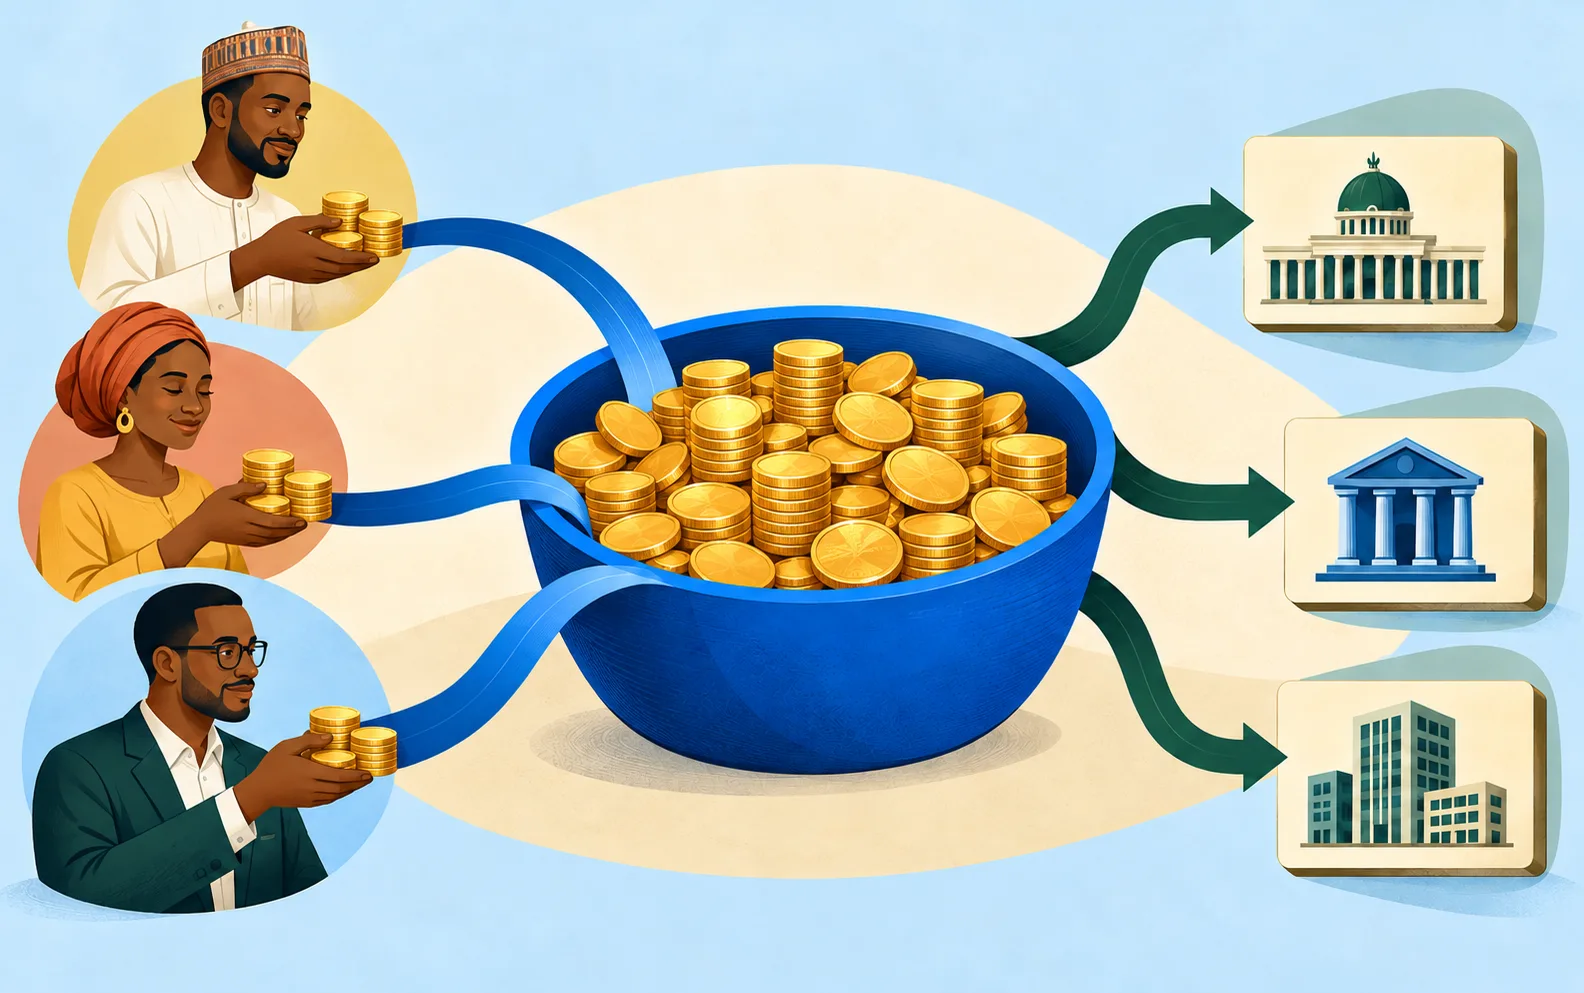
A Money Market Fund (MMF) bridges that gap. A money market fund is an open-ended mutual fund, regulated in Nigeria by the Securities and Exchange Commission (SEC) as a collective investment scheme, that pools money from thousands of individuals and institutions to buy low-risk, short-term debt instruments such as Treasury Bills, bank fixed deposits, and corporate commercial papers. Its main purpose is to preserve your capital, let you withdraw your cash within a few working days, and pay you an interest yield that tracks short-term wholesale money market rates, often starting with as little as ₦5,000 or ₦10,000.
KEY TAKEAWAYS
- Pooled buying power unlocks institutional rates: By combining your ₦5,000 or ₦100,000 with billions of Naira from other savers, a money market fund gives you access to Treasury Bill and bulk fixed-deposit yields that normally require millions of Naira.
- Strict maturity rules keep risk low: Under SEC Nigeria regulations, a money market fund can only buy debt instruments maturing within one year (up to 366 days), and the weighted average maturity of the entire portfolio must not exceed 90 days.
- Interest accrues daily and pays out or compounds quarterly: Your return builds up every day based on the fund's current yield, and at the end of each quarter you can either receive the cash in your bank account or reinvest it automatically to buy more units.
- Yields float with market rates and principal is not NDIC-insured: Unlike a fixed deposit that locks in one rate, a money market fund's yield rises and falls with CBN policy rates and Treasury Bill auctions. Fund units are regulated by the SEC and held by an independent custodian, but they are not covered by Nigeria Deposit Insurance Corporation (NDIC) bank insurance.
- Early withdrawals only affect accrued interest, not your principal: Most Nigerian funds set a minimum holding window of 14 to 90 days. Withdrawing before that window closes usually triggers a 20% penalty on the interest earned during that short period, while your original deposit remains intact.
Two Quick Basics Before You Invest
Before looking at how a fund calculates your return, it helps to clear up two terms that often confuse first-time investors.
1. What Is the "Money Market"?
Despite the name, the money market is not a stock market where people trade company shares. In finance, the money market is the segment of the financial system where governments, commercial banks, and large corporations borrow and lend cash for short periods of one year or less. Because these loans mature in 30, 91, 182, or 364 days, they are much less sensitive to the sharp price swings seen in long-term bonds or company stocks.
2. Who Actually Holds Your Money? (The Three-Party Safety Structure)
A common fear among beginners in Nigeria is simple: What if the investment company closes down or runs away with my money?
In a registered collective investment scheme, the fund manager is legally prohibited from keeping your money in its own company bank account. Under the Investment and Securities Act and SEC Nigeria Rules on Fund Management Products and Custodians, every approved money market fund must operate with three separate licensed institutions:
- The Fund Manager: The SEC-licensed asset management company (such as Stanbic IBTC Asset Management, United Capital Asset Management, ARM Investment Managers, Chapel Hill Denham, or FBNQuest) that researches interest rates and decides which Treasury Bills or fixed deposits to buy.
- The Custodian: A separate financial institution (typically the custody arm of a major commercial bank with a minimum net worth requirement under SEC rules) that actually holds the fund's cash and securities in the fund's name. The fund manager cannot move cash out of the custodian's vault for its own company expenses.
- The Trustee: An independent licensed trustee company that supervises the fund manager on behalf of all unitholders and enforces the rules written in the fund's Trust Deed.
If a fund manager ever faces financial trouble of its own, the fund's assets remain ring-fenced with the custodian, and the trustee can transfer management of the fund to another SEC-licensed manager.
What Does a Nigerian Money Market Fund Invest In?
When you buy units in a Nigerian money market fund, the fund manager spreads the pool across four short-term asset classes within limits set by the SEC and the fund's prospectus, such as those detailed in the Norrenberger Money Market Fund Prospectus and the United Capital Money Market Fund Factsheet (September 2026):
- Short-Term Federal Government Securities (25% to 80% of the pool): Primarily Nigerian Treasury Bills (NTBs) issued by the Federal Government through the CBN for 91, 182, or 364 days, along with CBN Open Market Operation (OMO) bills. These carry sovereign backing from the Federal Government of Nigeria.
- Fixed Deposits and Bank Placements (20% to 75% of the pool): Because a money market fund manages tens or hundreds of billions of Naira, the fund manager can negotiate wholesale fixed-deposit interest rates with top-rated Nigerian commercial and merchant banks that are far higher than what an individual gets walking into a banking hall with ₦100,000.
- Commercial Papers (CPs): Short-term debt notes (usually maturing in 90 to 270 days) issued by large, creditworthy Nigerian companies to finance inventory or working capital. Commercial papers usually pay slightly higher interest than Treasury Bills to compensate for corporate credit risk.
- Cash Reserves (Typically up to 5%): A small slice of liquid cash kept on hand to pay investors who request daily redemptions without forcing the manager to sell securities early.
To prevent fund managers from locking your money into long-term debt, SEC Nigeria rules require every instrument in a money market fund to mature within 365 or 366 days, and the weighted average maturity (WAM) across all holdings in the fund must not exceed 90 days.
How a Money Market Fund Makes Money (For You and for the Manager)
Understanding how cash flows through the fund helps you read a monthly fund factsheet without confusion.
How the Fund Manager Gets Paid
A money market fund is not a charity. The fund manager earns revenue by charging an annual management fee (typically between 1.0% and 1.5% of the fund's net asset value per year, subject to 7.5% Value Added Tax). The fund also pays regulated fees to the custodian, trustee, registrar, and external auditor. Together, these operating costs are published on the fund's factsheet as the Total Expense Ratio (TER). For example, the United Capital Money Market Fund September 2026 Factsheet discloses a 1.0% management fee and a 1.3% total expense ratio.
How You Earn Your Return
Crucially, the effective annual yield published by SEC-regulated Nigerian money market funds is stated net of management fees and fund expenses. If a fund reports a net effective yield of 16.00% per annum for the day, the manager's fee has already been deducted before that 16.00% figure is announced.
Most Nigerian money market funds maintain a constant Net Asset Value (NAV) per unit, usually ₦1.00 per unit (or ₦100.00 per unit in some older or specialized funds, as seen in the FSL Money Market Fund Prospectus and Norrenberger Prospectus). Instead of your unit price jumping up and down every afternoon like a stock, your unit price stays steady at par value while your interest accrues daily. At the end of every calendar quarter (March, June, September, and December), the fund distributes your accumulated interest in one of two ways:
- Cash Payout: The fund transfers your quarterly interest in cash to your commercial bank account, while your original units remain in the fund.
- Automatic Reinvestment: The fund uses your quarterly interest payout to buy new units in the fund at ₦1.00 (or ₦100.00) each, so your next quarter's daily interest is calculated on a larger unit balance.
Worked Example: ₦500,000 in a Bank Savings Account vs. a Money Market Fund
Let's walk through an illustrative one-year scenario using ₦500,000 to see how daily accrual, quarterly reinvestment, taxes, and early withdrawal rules work in practice.
Suppose you have ₦500,000 you will not need for twelve months, and you compare three choices:
- Option 1 (Commercial Bank Savings Account): Under Section 1.2 of the CBN Guide to Bank Charges, banks must pay a minimum of 30% of the Monetary Policy Rate (MPR) per annum on savings accounts, provided you do not make more than four withdrawals in a month. With the MPR set at 23.00% in the CBN's September 2026 Monetary Policy Committee Communiqué No. 164, that statutory floor is 6.90% per annum before 10% Withholding Tax (WHT).
- Option 2 (Money Market Fund with Quarterly Cash Payouts): You invest ₦500,000 in a fund averaging an illustrative 16.00% per annum net yield across the year, and you take your interest in cash every quarter.
- Option 3 (Money Market Fund with Automatic Quarterly Reinvestment): You invest the same ₦500,000 at an average 16.00% per annum yield, and you set your account to reinvest each quarterly distribution automatically.
Under the Nigeria Tax Act 2025, as analyzed by Qeeva Advisory and Lukefield Finance, a 10% Withholding Tax (WHT) applies to interest on bank savings, Treasury Bills, and collective investment scheme distributions (which serves as the final tax for individual investors), while gains from redeeming units in an SEC-approved scheme are exempt from Capital Gains Tax. Because some funds deduct WHT on underlying portfolio interest before publishing their net yield while others withhold at distribution, the table below shows both pre-WHT and post-10%-WHT outcomes so you can compare the exact numbers:
1-Year Scenario (₦500,000 Starting Principal) | Headline Annual Rate | Gross Interest Earned (Before 10% WHT) | Net Interest Earned (After 10% WHT) | Total Account Value After 12 Months (After WHT) |
Bank Savings (4 or fewer withdrawals/mo) | 6.90% p.a. | ₦34,500.00 | ₦31,050.00 | ₦531,050.00 |
Bank Savings (5+ withdrawals every month) | 0.00% p.a. (forfeited) | ₦0.00 | ₦0.00 | ₦500,000.00 |
Money Market Fund (Cash Payout Quarterly) | 16.00% p.a. | ₦80,000.00 | ₦72,000.00 (paid to bank) | ₦500,000.00 (+ ₦72,000.00 cash) |
Money Market Fund (Auto-Reinvested Quarterly) | 16.00% p.a. | ₦84,929.28 | ₦75,982.15 | ₦575,982.15 (or ₦584,929.28 if yield is already net of tax) |
What if an emergency happens after 20 days and you have to withdraw your ₦500,000 from a fund that has a 30-day minimum holding period and a 20% early redemption penalty?
- Over 20 days at 16.00% per annum, your ₦500,000 accrues ₦500,0000.16(20365)=₦4,383.56 in interest.
- Because you exited before Day 30, the 20% penalty applies only to that ₦4,383.56 interest, deducting ₦876.71.
- You still receive your full ₦500,000.00 principal plus the remaining ₦3,506.85 in accrued interest.
Check Your Priorities First: Money Market Fund vs. Other Low-Risk Nigerian Options
Before moving your savings into a money market fund, define what this specific pile of Naira needs to do for you over the next twelve months. Ask yourself four questions:
- How fast might I need the cash? If you need to pay a hospital deposit or mechanic at 9:00 p.m. on a Saturday, you need instant NIP bank transfer access. A money market fund takes 1 to 3 working days (24 to 72 business hours) to process a withdrawal into your bank account.
- How much capital am I starting with? If you have ₦5,000 to ₦50,000, a money market fund or FGN Savings Bond is open to you, whereas direct primary-market Treasury Bills require ₦50,001,000 (and secondary-market T-Bills through banks or stockbrokers usually start around ₦100,000).
- Do I think interest rates are going up or coming down? Money market fund yields float. When the CBN cut the Monetary Policy Rate from 26.50% to 23.00% in September 2026, primary auction stop rates on 364-day Treasury Bills dropped from 16.62% to 15.89%, as documented in the United Capital September 2026 Factsheet. When market rates fall, a money market fund's yield drifts downward over the next 30 to 90 days. If you want to lock in today's rate for a full year or two regardless of future CBN rate cuts, a 364-day Treasury Bill or a 2-to-3-year FGN Savings Bond protects your rate.
- How important is tax exemption vs. liquidity? Long-term FGN Bonds and FGN Savings Bonds are completely exempt from income tax and withholding tax under Nigerian law, whereas bank savings, Treasury Bills, and taxable fund distributions attract 10% WHT.
Use the comparison table below to match your money to the right vehicle:
Feature / Decision Criterion | Commercial Bank Savings Account | SEC-Regulated Money Market Fund | Nigerian Treasury Bills (NTBs) | FGN Savings Bond (2-Year or 3-Year) |
Primary Regulator | Central Bank of Nigeria (CBN) | Securities and Exchange Commission (SEC) | CBN / Debt Management Office (DMO) | Debt Management Office (DMO) / SEC |
Typical Minimum Entry | ₦0 to ₦1,000 | ₦5,000 to ₦10,000 | ₦50,001,000 (Primary Auction); ~₦100,000 (Secondary Market) | ₦5,000 (multiples of ₦1,000; max ₦50,000,000) |
Recent Indicative Rate (Sept/Oct 2026) | Minimum 6.90% p.a. (30% of 23% MPR) | ~15.5% to 21.4% p.a. (floating net yield; varies by fund) | 15.50% to 15.89% p.a. (Sept 23, 2026 auction stop rates) | 13.071% p.a. (2-Yr) and 14.071% p.a. (3-Yr) in Oct 2026 offer |
How Rate Behaves | Varies with MPR; forfeited for the month if withdrawals exceed 4 | Variable (floats daily) as underlying 30-to-90-day bills roll over | Fixed for the chosen 91, 182, or 364-day tenor if held to maturity | Fixed for the full 2-year or 3-year tenor |
Access to Principal (Liquidity) | Instant (24/7 via NIP transfer) | 1 to 3 working days (20% penalty on accrued interest if redeemed before 14 to 90 days) | Locked until maturity (early sale on secondary market depends on current market prices) | Locked for 2 to 3 years (can be sold on NGX secondary market at prevailing market price) |
Protection & Custody | Insured by NDIC up to ₦5,000,000 per depositor in commercial banks | Not NDIC-insured; assets ring-fenced with an SEC-licensed Custodian and Trustee | Backed by the full faith and credit of the Federal Government of Nigeria | Backed by the full faith and credit of the Federal Government of Nigeria |
Withholding Tax (WHT) Status | 10% WHT deducted at source on interest | 10% WHT applies to taxable interest/distributions (exempt from CGT on unit redemption) | 10% WHT applies to interest under current tax rules | Exempt from Personal Income Tax, Company Income Tax, and WHT |
Are Money Market Funds Really "Risk-Free"? 4 Limitations to Know
Many social media threads and fintech advertisements describe money market funds as "100% risk-free savings." That description glosses over real financial distinctions.
As both the U.S. Securities and Exchange Commission (SEC) and the Federal Reserve Bank of New York explain in their foundational investor guidance, money market funds are low-risk investment products, not insured bank deposits, and they can experience yield drops or credit losses under stressed conditions. Before you invest in a Nigerian money market fund, weigh these four practical risks:
1. No NDIC Deposit Insurance
Your commercial bank deposit is insured by the Nigeria Deposit Insurance Corporation (NDIC) up to ₦5,000,000 (and up to ₦2,000,000 in a licensed microfinance bank) if the bank fails. A money market fund is an investment portfolio, so NDIC insurance does not apply. Your protection comes from SEC regulation, independent bank custody, and the credit quality of the bills and banks the fund lends to.
2. Corporate Commercial Paper Default Risk
A money market fund that invests 70% of its pool in Federal Government Treasury Bills and top-rated tier-1 bank placements carries very low default risk. However, some fund managers chase higher yields by allocating a larger slice of the portfolio to higher-yielding corporate commercial papers. If a company that issued commercial paper to the fund defaults on its debt, the fund's return will drop, and in severe cases the fund's unit value could fall below par.
3. Interest Rate and Inflation Risk
Because a money market fund's holdings mature inside 90 days on average, the fund is constantly reinvesting cash at whatever interest rates exist that month. When headline inflation in Nigeria stood at 14.63% in September 2026 (per the CBN Macroeconomic Indicators), a fund yielding 16.5% delivered a modest positive real return of roughly 1.87 percentage points above inflation. If inflation spikes above money market yields, your Naira balance still grows, but its real purchasing power declines.
4. Weekend and Public Holiday Settlement Delays
Most Nigerian funds pay out redemptions within one to three working days. If you submit a withdrawal request at 4:00 p.m. on Friday before a Monday public holiday, the cash may not hit your commercial bank account until Tuesday or Wednesday afternoon. Never keep your very last ₦50,000 for immediate food, fuel, or medical emergencies locked inside a mutual fund.
How to Choose and Open a Money Market Fund in Nigeria
You do not need a stockbroker or a physical visit to Marina or Victoria Island to open an account. Most SEC-licensed asset managers let you open and fund an account online in ten minutes using your Bank Verification Number (BVN), National Identification Number (NIN), a valid ID card, and a utility bill.
Use these four checks to pick a strong fund:
- Confirm SEC Registration First: Check the SEC Nigeria list of registered capital market operators and collective investment schemes to confirm that both the fund manager and the specific Money Market Fund are approved. If you use a third-party savings or wealth app, read its terms to verify whether you are buying units in a named SEC-registered money market fund or lending money to a private cooperative.
- Inspect the Monthly Factsheet Asset Mix: Download the fund's latest one-page monthly factsheet from the manager's website. Check what percentage is held in Short-Term FGN Securities (Treasury Bills) and rated bank fixed deposits versus corporate commercial papers. Don't pick a fund solely because it had the highest yield last month; check whether it took extra corporate credit risk to get that yield.
- Check the Fund Rating and Expense Ratio: Look for an independent credit quality and volatility rating on the factsheet from an SEC-registered rating agency (such as Agusto & Co. or GCR Ratings, where ratings like Aa or Aa- indicate high credit quality and low conservative risk). Compare the Total Expense Ratio (TER) across funds, since lower expenses leave more of the gross return in your pocket.
- Verify the Minimum Holding Period and Bank Transfer Channels: Check whether the fund enforces a 14-day, 30-day, 90-day, or 180-day minimum holding period before penalty-free withdrawals, and ask whether the manager provides a dedicated virtual bank account number (NUBAN) for your fund account so you can top it up directly from your regular mobile banking app without paying card-processing fees.
Once your account is active, keep one to two weeks of immediate cash in your regular bank account for daily transfers, move the rest of your emergency buffer or short-term target savings (for annual rent, school fees, or tax reserves) into the money market fund, and switch your dividend preference to Automatic Reinvestment until the month you actually need to spend the cash.
Sources and review
Written by Sam Olumide, reviewed and published by Fincalcz Editorial Team. Last updated November 2, 2026. This article is for educational and informational purposes only and does not constitute individualized financial, investment, tax, or legal advice. Always review the official fund prospectus and latest factsheet or consult a licensed financial professional before investing.
- Securities and Exchange Commission (SEC) Nigeria: Executed Rules on Regulation of Fund Management Products and Nominee/Custodian Operations and SEC New Rules and Amendments on Collective Investment Schemes. Used for Nigerian collective investment scheme registration rules, the mandatory separation of Fund Manager, Custodian, and Trustee roles, and regulatory oversight of unit trust schemes.
- United Capital Asset Management Ltd: United Capital Money Market Fund Factsheet (September 2026) and Stanbic IBTC Asset Management: Stanbic IBTC Money Market Fund Factsheet (February 2026). Used for current 2026 Nigerian money market fund minimum investment amounts (₦5,000 to ₦10,000), par unit values, management fees (1.0%), total expense ratios (1.3%), Agusto & Co. fund ratings, and September 2026 Nigerian Treasury Bill auction stop rates (15.50%, 15.80%, and 15.89%).
- Norrenberger Investment and Capital Management Ltd: Norrenberger Money Market Fund Prospectus, NovaMBL Asset Management Ltd: Nova Prime Money Market Fund Prospectus, and FSL Asset Management Ltd: FSL Money Market Fund Prospectus. Used to corroborate the 90-day maximum weighted average maturity (WAM) limit, the 365/366-day maximum instrument maturity ceiling, the 5% cash-holding guideline, minimum holding periods (30 to 180 days), and the standard 20% flat penalty on accrued income for redemptions made during the lock-in window.
- Central Bank of Nigeria (CBN): The Guide to Charges by Banks, Other Financial and Non-Bank Financial Institutions, Monetary Policy Committee Communiqué No. 164 (September 2026), and CBN Macro Economic Indicators. Used for the Section 1.2 statutory minimum savings interest rate (30% of MPR per annum, forfeited if monthly withdrawals exceed four) and September 2026 macroeconomic benchmarks (23.00% MPR and 14.63% headline inflation).
- Debt Management Office (DMO) Nigeria: Public Notice on the New Market Structure for FGN Securities and Stanbic IBTC Bank: Nigerian Treasury Bills Product Guide and FAQs. Used to verify the ₦50,001,000 primary-market minimum subscription for Nigerian Treasury Bills, secondary-market minimum thresholds (₦100,000), and FGN Savings Bond subscription limits (₦5,000 minimum to ₦50,000,000 maximum), corroborated for October 2026 FGN Savings Bond coupon rates (13.071% and 14.071%) by Nigeria Housing Market.
- Qeeva Advisory: Taxation of Investment Income Under Nigeria Tax Act 2025 and Lukefield Finance: Taxable Accounts Explained for Nigerian Investors. Used for the 2026 Nigerian tax treatment of investment income under the Nigeria Tax Act 2025, including the 10% Withholding Tax (WHT) on bank interest, Treasury Bills, and unit trust distributions (as final tax for individuals), the Capital Gains Tax exemption on redeeming units in an SEC-approved collective investment scheme, the 7.5% VAT on fund management fees, and the full tax exemption on FGN Bonds.
- Nigeria Deposit Insurance Corporation (NDIC): NDIC Frequently Asked Questions (FAQs), U.S. Securities and Exchange Commission (Investor.gov): Money Market Funds, and Federal Reserve Bank of New York: Money Market Funds Overview. Used to distinguish deposit insurance on bank accounts (up to ₦5,000,000 for Nigerian commercial banks and ₦2,000,000 for microfinance banks) from un-insured mutual fund units and to corroborate the credit and liquidity risks of money market funds.
How We Calculate Our Examples
The Naira (₦) scenarios in this article are illustrative calculations designed to compare interest accrual, quarterly reinvestment, tax deductions, and early-redemption penalties across Nigerian savings and money market products; they are not guaranteed quotes from any specific fund manager. In the ₦500,000 one-year comparison table, the commercial bank savings rate of 6.90% per annum is calculated as 30% × 23.00% (the CBN Monetary Policy Rate as of September/October 2026), yielding ₦500,000 × 0.069 = ₦34,500.00 gross interest, or ₦31,050.00 net after deducting 10% Withholding Tax (WHT), assuming four or fewer withdrawals per month. For the Money Market Fund at an illustrative 16.00% per annum net yield, taking quarterly cash payouts produces ₦500,000 × 0.16 = ₦80,000.00 gross (₦72,000.00 after 10% WHT) while leaving the ₦500,000 principal unchanged. When quarterly distributions are automatically reinvested over 4 equal quarters, the pre-WHT ending balance is calculated as ₦500,000 × (1 + 0.16 / 4)4 = ₦584,929.28 (₦84,929.28 in compound interest, an effective annual yield of 16.99%), and the post-10%-WHT reinvested balance is calculated at a net annual rate of 16.00% × 0.90 = 14.40% (3.60% per quarter) as ₦500,000 × (1 + 0.036)4 = ₦575,982.15 (₦75,982.15 net gain, an effective net yield of 15.20%). In the 20-day early withdrawal example, accrued interest is calculated on a 365-day year basis as ₦500,000 × 0.16 × (20 ÷ 365) = ₦4,383.56, and the 20% flat penalty (₦4,383.56 × 0.20 = ₦876.71) is deducted solely from that accrued income, leaving the ₦500,000 principal intact. In real-world funds, daily yields fluctuate with money market rates, so actual quarterly payouts vary day by day.